June 2026 was a record month for space capital. SpaceX completed the largest IPO ever, raising about $75B, and Rocket Lab agreed to acquire Iridium in a roughly $8B deal. Venture funding stayed strong: Impulse Space raised a $500M Series D and has more than 200 open roles, ICEYE closed a €450M primary round (over €1B including secondary), Isar Aerospace raised €270M, and Apex added more than $200M after doubling its headcount to 350+.
Government demand was equally strong. Space Systems Command awarded Boeing $2B for two MUOS narrowband satellites and Lockheed Martin $514M for two more GPS IIIF satellites, ESA signed a €700M contract for Sentinel-1 Next Generation, and NASA awarded about $590M in lunar deliveries to Astrobotic, Intuitive Machines, and Firefly. Rocket Lab’s VICTUS HAZE mission set a responsive-launch benchmark, lifting off less than 17 hours after notice.
Facility news pointed to more production hiring, led by Vast’s plan for 657 jobs in Long Beach, SpaceX’s Gigasat factory in Texas, and new rocket and satellite factories from NordSpace and BlackVe. On the downside, Paragon Space Development cut about 90 jobs in Arizona and Colorado after its Gateway subcontract ended.
Top 7 Hiring Signals
SpaceX Completes the Largest IPO Ever
SpaceX priced its Nasdaq IPO on June 11 at $135 per share, raising about $75B at a valuation of roughly $1.75T, and began trading on June 12. Beyond the headline, public-market capital and stock-based compensation strengthen SpaceX’s ability to recruit across Starship, Starlink, Starshield, and its new orbital-compute ambitions, and raise the bar for competing employers.
Impulse Space Raises $500M and Has 200+ Open Roles
Impulse Space’s $500M Series D, co-led by 137 Ventures and Banner Ventures, brings its total funding above $1B. The company has more than doubled its headcount and lists over 200 open roles across Redondo Beach, Mojave, Boulder, and Washington, D.C., with demand concentrated in propulsion, vehicle engineering, manufacturing, test, and operations.
ICEYE’s €450M primary Series F, led by General Atlantic, comes alongside a secondary placement that takes the total above €1B and values the company at more than €10B. With over 1,000 staff already, ICEYE is expanding its global footprint and sovereign intelligence offering, supporting hiring in satellite production, data products, and customer delivery.
Space Systems Command awarded Boeing $2B to build two MUOS Service Life Extension narrowband communications satellites, displacing incumbent Lockheed Martin, with launches no earlier than 2031. A multi-year program of this size sustains demand in El Segundo for satellite systems engineering, payload and RF design, integration and test, and cleared program roles.
California awarded Vast a CalCompetes grant tied to an $87M expansion of its space station R&D and manufacturing in Long Beach, with 657 new jobs planned. It is the clearest explicit headcount commitment of the month and points to demand in structures, life-support, avionics, manufacturing, and test.
On June 30, NASA awarded CLPS missions to Astrobotic ($297.9M for two deliveries), Intuitive Machines (up to $148.3M for a production-line Nova-C lander), and Firefly ($144.2M for an accelerated Blue Ghost mission), all targeting 2028. Lander work supports hiring in GNC, propulsion, thermal, avionics, payload integration, and mission operations.
Apex’s growth round, led by Glade Brook Capital at a $2.3B valuation, funds a 30,000 sq. ft. expansion of its Factory One campus, more in-house subsystems, and satellite buses built ahead of orders. Headcount has already more than doubled to 350+, a strong signal for manufacturing, integration and test, and supply-chain hiring.
SpaceX (United States) – IPO, ~$75B (June 11). The largest IPO ever, valuing the company at roughly $1.75T. Source.
Impulse Space (United States) – Series D, $500M (June 2). Scales production of its in-space vehicles and propulsion, with 200+ open roles. Source.
ICEYE (Finland / Europe) – Series F, €450M primary (June 9), with secondary bringing the total above €1B. Expands its global footprint and sovereign intelligence systems. Source.
Isar Aerospace (Germany / Europe) – Series D, €270M (June 9). Serial production of the Spectrum rocket and a new launch site in Canada. Source.
Apex (United States) – Growth round, $200M+ (June 5) at a $2.3B valuation. Expands Factory One and builds satellite buses ahead of orders. Source.
Axiom Space (United States) – Financing extension, $175M (June 4), bringing the round to $525M+. Supports Axiom Station and AxEMU spacesuit production. Source.
ElevationSpace (Japan) – Series B, ¥6.4B (~$40M) (June 19). Commercial reentry and return-from-orbit services. Source.
Dawn Aerospace (New Zealand / Netherlands) – Series B, $25M (June 16). Satellite thrusters, in-space refueling, and the Aurora spaceplane, with new U.S. and EU teams. Source.
Unastella (South Korea) – Series B, $24M (June 1). More orbital launches and engine development. Source.
NewOrbit Space (United Kingdom) – Series A, €16M (~$18.5M) (June 8). A first VLEO mission with air-breathing propulsion and a Thames Valley production facility. Source.
Katalyst Space (United States) – Series A, $12M (June). The NEXUS servicing robot for a first GEO mission in 2027. Source.
FOSSA Systems (Spain / Europe) – Funding round, €9.25M (~$10.5M) (June 24). Expansion toward a 140-satellite IoT constellation. Source.
Rocket Lab → Iridium (United States) – Acquisition, ~$8B (June 29). Adds an L-band satellite network and recurring service revenue; closing expected mid-2027. Source.
Quantum Space (United States) – SPAC merger with Inflection Point VI, $1.2B post-money including a $300M PIPE (June 8). Funds Ranger maneuverable spacecraft. Source.
MDA Space → Blue Canyon Technologies (Canada / United States) – Acquisition from RTX, $620M (June 19). Brings about 400 Denver-area staff and entry into U.S. defense work. Source.
EQT → Exolaunch (Germany / Europe) – Private-equity acquisition, undisclosed (June 18). Scales the rideshare and deployment provider internationally. Source.
Firefly Aerospace → Space-ng (United States) – Acquisition, undisclosed (June 25). Adds AI vision navigation for Blue Ghost landers and Elytra. Source.
Contracts and Grants
U.S. Space Force / Space Systems Command → Boeing (El Segundo, CA) – $2B (June 24). Two MUOS Service Life Extension narrowband satellites, launching no earlier than 2031. Read more.
ESA → Thales Alenia Space (Italy), with Airbus Defence and Space (Germany) – €700M (June 10). Two Sentinel-1 Next Generation radar satellites for Copernicus. Read more.
U.S. Space Force / Space Systems Command → Lockheed Martin (Littleton, CO) – $514.4M (June 15). GPS IIIF satellites 23 and 24, bringing the GPS IIIF order to 14 satellites. Read more.
U.S. Space Force / Space Systems Command → Viasat and Intelsat (U.S.) – $437.7M combined (June 9). The first two Protected Tactical SATCOM-Global anti-jam satellites, launching in 2028. Read more.
NASA → Astrobotic (Pittsburgh, PA) – $297.9M (June 30). Two CLPS lunar deliveries landing in late 2028, announced with a broader Moon Base update. Read more.
NASA → Intuitive Machines (Houston, TX) – up to $148.3M (June 30). A sixth CLPS task order using a production-line Nova-C lander. Read more.
NASA → Firefly Aerospace (Cedar Park, TX) – $144.2M (June 30). An accelerated Blue Ghost lunar mission, Firefly’s sixth contracted lunar delivery. Read more.
NASA SEWP VI → 1,490 vendors (U.S.) – ~$60B ceiling (June). An expanded IT contract vehicle with ordering from November through 2036. Read more.
NASA → Hydrosat (Washington, D.C.) – Spot on a $476M IDIQ (June 24). Commercial thermal-infrared Earth observation data purchases. Read more.
ESA / UK Space Agency → AAC Clyde Space (Glasgow, UK) – €10.9M (June 25). An in-orbit demonstration for the INFLECION maritime VDES constellation. Read more.
Expansions and Layoffs
Vast (Long Beach, CA) – CalCompetes award for an $87M expansion of space station R&D and manufacturing, with 657 jobs planned (June 22). Read more.
SpaceX (Bastrop, TX) – Unveiled plans for an 11M sq. ft. “Gigasat” factory to build orbital-compute satellites, solar cells, and circuit boards (June 8). No headcount was given. Read more.
NordSpace (Markham, ON) – Opened Rocket Factory 1, a 60,000 sq. ft. plant with room for up to 255 staff (June 16). Read more.
BlackVe (Albuquerque, NM) – Headquarters expansion with a 50,000 sq. ft. satellite factory and 152 jobs over ten years (June 19). Read more.
Scout Space (Merrifield, VA) – New optical-sensor manufacturing site with 31 jobs (June 9). Read more.
Space Tango (Lexington, KY) – $7.4M headquarters expansion with labs and mission operations, adding 25 jobs (June 25). Read more.
Paragon Space Development (Tucson, AZ and Colorado) – Layoffs of about 90 jobs (77 in Arizona, 15 in Colorado) after its Gateway HALO life-support subcontract ended (June 12). Read more.
Launch and Regulation
Rocket Lab / U.S. Space Force (VICTUS HAZE) – Electron launched the TacRS-4 space domain awareness satellite 16 hours and 42 minutes after notice to launch (June 19), a responsive-space benchmark. Read more.
CASC / Long March 12B (China) – Maiden flight of a Falcon 9-like reusable-design rocket with Qianfan satellites (June 1). Read more.
JAXA / MHI H3-30S (Japan) – First flight of the booster-less H3 variant (June 12), returning H3 to flight after its December 2025 failure. Read more.
Arianespace / Amazon Leo (Europe) – First Ariane 64 with upgraded P160C boosters carried 36 Amazon Leo satellites, the largest Leo batch so far (June 17). Read more.
SpaceX / Starfall (United States) – Demonstration of a new reentry capsule for returning up to 1,000 kg of cargo from orbit (June 23). Read more.
Blue Origin / LC-36 (United States) – Pad rebuild under way after the May 28 static-fire explosion, with New Glenn still targeting a return to flight in 2026 (June 26). Read more.
Office of Space Commerce (United States) – TraCSS began onboarding national government accounts from other countries (June 9). Read more.
FCC Space Bureau (United States) – New NGSO processing rounds opened in the Ku-, Ka-, and V-bands (June 5), with a July 6 filing cut-off. Read more.
Roles in Demand, June 2026
Engineering
Propulsion engineering
Spacecraft systems engineering
GNC (guidance, navigation & control)
RF & payload engineering
Avionics
Structures & life support
Manufacturing & Operations
Satellite & vehicle production
Integration & test
Supply chain
Launch operations
Mission operations
Software & Analysis
Flight software
Autonomy & vision navigation
SAR & geospatial data products
Ground systems software
Compliance & Assurance
Mission assurance
Quality engineering
Spectrum & licensing
Security / cleared program support
Corporate development & integration (M&A)
Key Regions
Southern California (U.S.)
Texas (U.S.)
Colorado (U.S.)
New Mexico (U.S.)
Canada
Finland
Germany
Italy
United Kingdom
Japan
Ready to take the next step?
Whether you're hiring or looking, we connect you with the space industry.
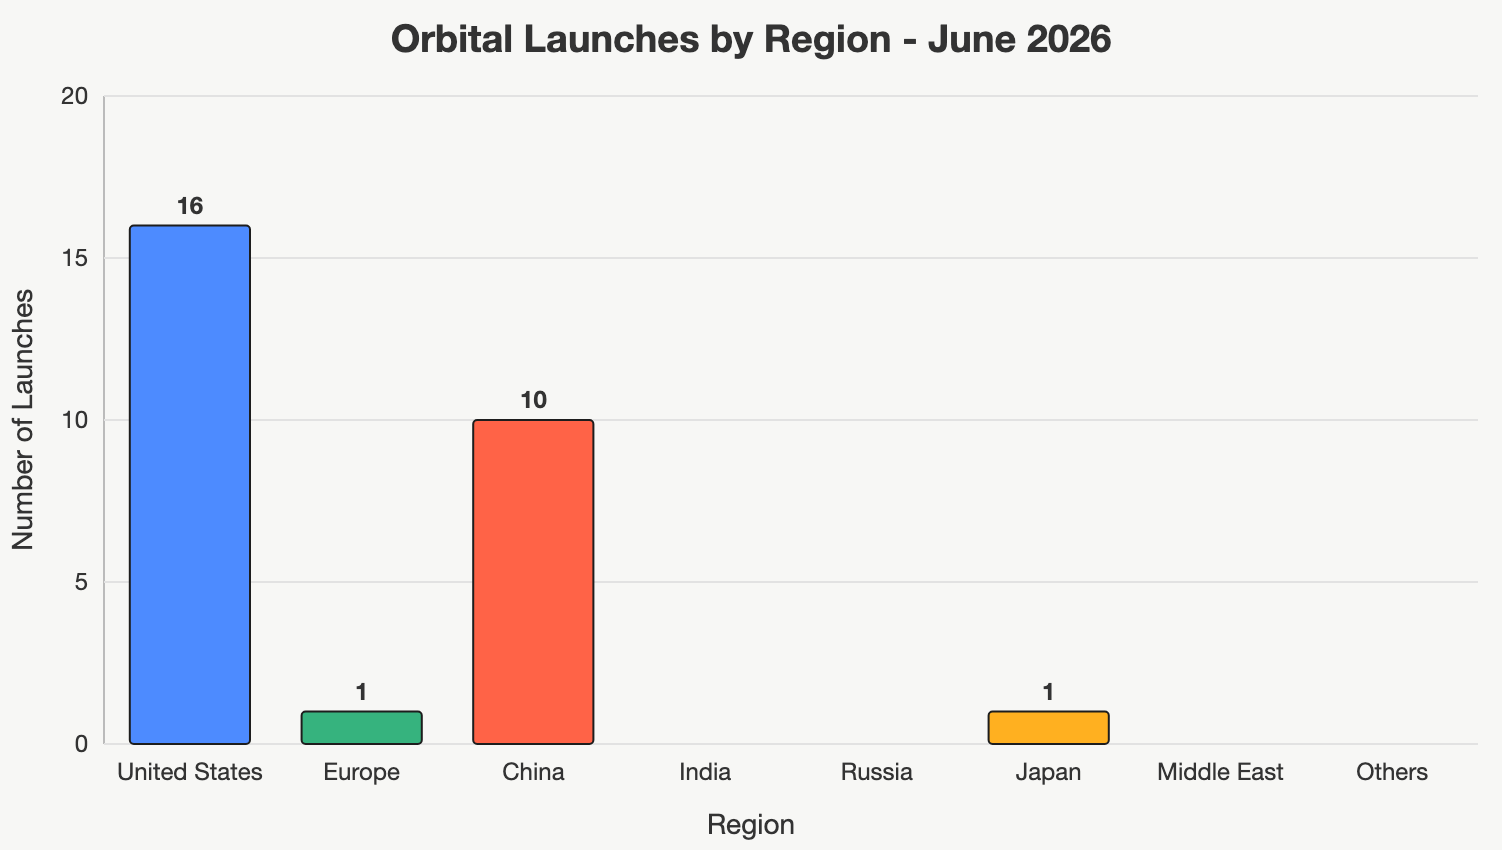
This bar chart visualizes orbital launch activity for June 2026, with a total of 28 attempts, all
successful. The United States led with 16 launches: 14 Falcon 9 flights (10 Starlink batches, AST
SpaceMobile's BlueBird 8–10, NROL-179, the Starfall demo, and SiriusXM SXM-11) and 2 Rocket Lab
Electron missions, including VICTUS HAZE for the U.S. Space Force. China contributed 10 launches,
including the maiden flight of Long March 12B and the return to flight of Long March 3B/E. Europe
recorded 1 launch, an Ariane 64 carrying 36 Amazon Leo satellites, and Japan flew the first H3-30S.
Rocket Lab's HASTE “CURVEBALL” flight, planned as suborbital, is not counted even though its
stages were catalogued in orbit. Russia, India, and the Middle East had no orbital launches this month.
Methodology and Sources
This report compiles June 2026 announcements from
Payload,
European Spaceflight,
SpaceNews,
FCC,
FAA, and
ESA STAR.
Events are scored on a five-point scale for expected hiring impact within 3 to 12 months.
Rankings weigh funding size, contract value, immediacy, and regional scope.
If you notice any discrepancies or missing information, please contact us at
team@spacejobsearch.com.